RHB Research has initiated coverage on Main Market-listed one-stop sustainable energy and engineering solutions provider Kinergy Advancement Bhd with a “buy” rating alongside a 48% sum-of-part (SOP)-based 60 sen target price over its 40.5 sen Friday (Sept 18) closing price.
For starters, the research house “likes Kinergy as an emerging independent power producer (IPP) player with the development of the 1.5GW (gigawatt) gas plant in Perlis”.
“While the plant will only come online in 2030, Kinergy will benefit from construction works and on-going engineering works for PETRONAS,” envisages analyst Max Koh in an initiating coverage note.
“The group will grow its concession assets to 1.6GW by 2031 vs 31MW (megawatt) currently.”
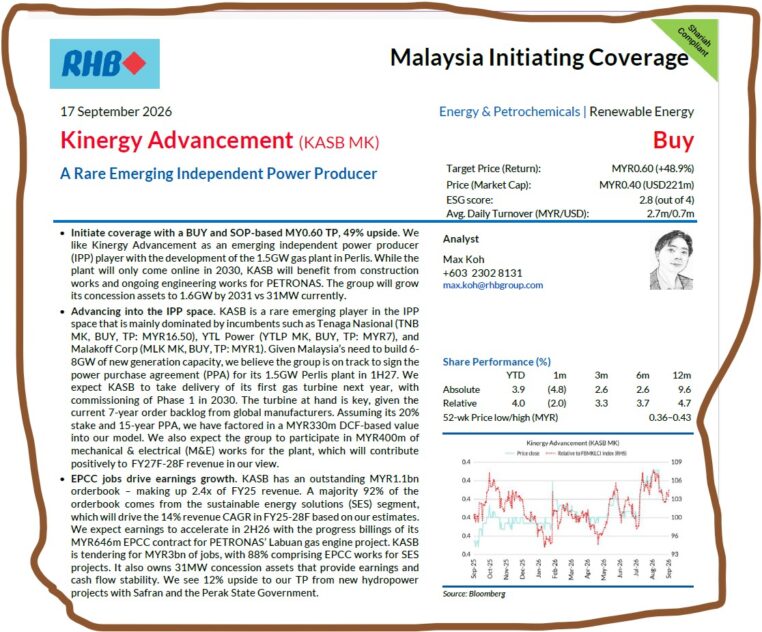
Delving further, RHB Research sees Kinergy as a rare emerging player in the IPP space that is mainly dominated by incumbents such as Tenaga Nasional Bhd, YTL Power International Bhd and Malakoff Corp Bhd.
“Given Malaysia’s need to build 6GW-8GW of new generation capacity, we believe the group is on track to sign the power purchase agreement (PPA) for its 1.5GW Perlis plant in 1H 2027,” projected the research house.
“We expect Kinergy to take delivery of its first gas turbine next year with commissioning of Phase 1 in 2030. The turbine at hand is key given the current seven-year order backlog from global manufacturers.”
‘Earnings expected to accelerate in 2H 2026’
Assuming its 20% stake and 15-year PPA, the research house has factored in a RM330 mil DCF (discounted cash flow)-based value into its model.
“We also expect the group to participate in RM400 mil of mechanical & electrical (M&E) works for the plant which will contribute positively to its FY2027F-FY2028F revenue.”
As it is, Kinergy has an outstanding RM1.1 bil orderbook which makes up 2.4x of the group’s FY2025 revenue, according to RHB Research.
Based on the research house’s estimates, a majority 92% of the orderbook comes from the group’s sustainable energy solutions (SES) segment which will drive the 14% revenue CAGR (compound annual growth rate) in FY2025-FY2028F.
“We expect earnings to accelerate in 2H 2026 with the progress billings of its RM646 mil EPCC (engineering, procurement, construction and commissioning) contract for PETRONAS’ Labuan gas engine project,” the research house noted.
Kinergy is tendering for RM3 bil of jobs with 88% comprising EPCC works for SES projects. It also owns 31MW concession assets that provide earnings and cash flow stability.
We foresee 12% upside to our target price from new hydropower projects with Safran and the Perak State Government.
Moving forward, RHB Research forecasts revenue to grow 21% in Kinergy’s FY2026 on stronger progress billings for the goup’s 120MW Labuan contract.
After factoring in a total RM1.1 bil outstanding orderbook and 10% pre-tax margin vs 8% last year, the research house expects earnings to grow 44%, 9% and 11% between FY2026 and FY2028.
“We derive our target price from ascribing a 19x target P/E (price-to-earnings ratio) on FY2027F recurring earnings and incorporating a DCF value (weighted average cost of capital: 6.9%, 80% debt and 20% stake in the plant) of RM330 mil for the 1.5GW gas plant,” justified the RHB Research.
“Our implied 24x FY2027F target P/E is close to Kinergy’s five-year +1SD (standard deviation) average P/E. We believe the premium is fair to reflect the 20% earnings CAGR (FY2025-2028F) for its existing businesses and prospects from the new gas plant.”
Nevertheless, the research house also incorporated a 4% ESG (environment, social and governance) discount to its target price given Kinergy’s unfavourable 2.8 score.
“Downside risks for the group include (i) delays in the 1.5GW gas plant’s commissioning; and (ii) margins compression,” added RHB Research. – Sept 19, 2026