MALAYSIA’S push to expand renewable energy capacity could gain fresh momentum after PETRA introduced an acceleration package aimed at making the CRESS programme more commercially viable.
Under the package, several measures were introduced, including:
(i) a 30% reduction in the System Access Charge (SAC) for firm supply, from 20 sen/kWh to 14 sen/kWh.
(ii) a mandatory 10-year contractual period between Renewable Energy Developers (REDs) and Green Consumers (GCs).
(iii) a strict requirement for projects benefiting from the special SAC rate to achieve COD by 31 Dec 2028.
CRESS awards are expected to gain momentum in quarter four calendar year 2026 (4QCY26) and 1QCY27.
CRESS projects have historically progressed slowly as renewable energy developers (REDs) and corporate buyers (GCs) took time to negotiate commercially viable terms.
However, the new acceleration package could change that dynamic, with projects benefiting from the special SAC rate required to achieve commercial operation by Dec 31, 2028.
According to Hong Leong Investment Bank (HLIB), the deadline is expected to push both developers and data centre (DC) offtakers to speed up negotiations and secure their projects.
“As a result, we expect CRESS activity to pick up, with more project announcements and deal-related news potentially emerging in 4QCY26 and 1QCY27,” said HLIB.
With solar projects generally taking around 18 to 24 months from construction to commissioning, the 2028 deadline creates a relatively narrow window for developers to secure contracts, achieve financial close and begin construction.
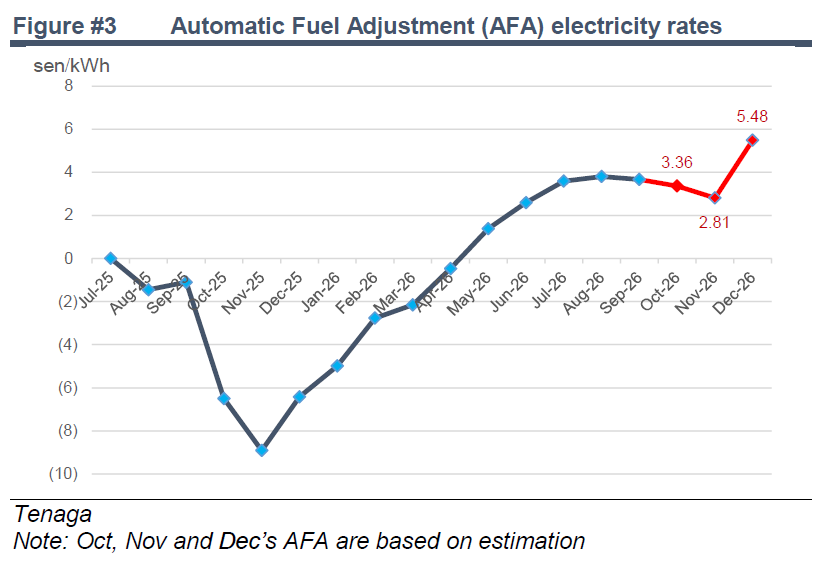
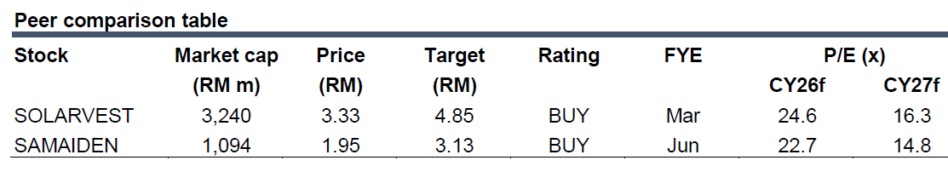
Against this backdrop, Solarvest and Samaiden are expected to secure their first CRESS project within the next three months.
CRESS could also offer developers stronger returns compared with the Large Scale Solar (LSS) programme. While LSS projects are awarded through competitive bidding, which can put pressure on tariffs and project margins, CRESS allows developers to negotiate pricing directly with corporate power buyers.
Tenaga’s DayOne CRESS project provides an indication of the potential returns, with the project estimated to deliver an attractive internal rate of return (IRR) of 12%.
This compares favourably with the estimated 6% to 8% IRR generated by previous LSS projects.
“Our back-of-the-envelope analysis suggests that CRESS projects could generally generate 9–11% IRRs, depending on PPA tenure, contracted tariff, land and financing costs,” said HLIB.
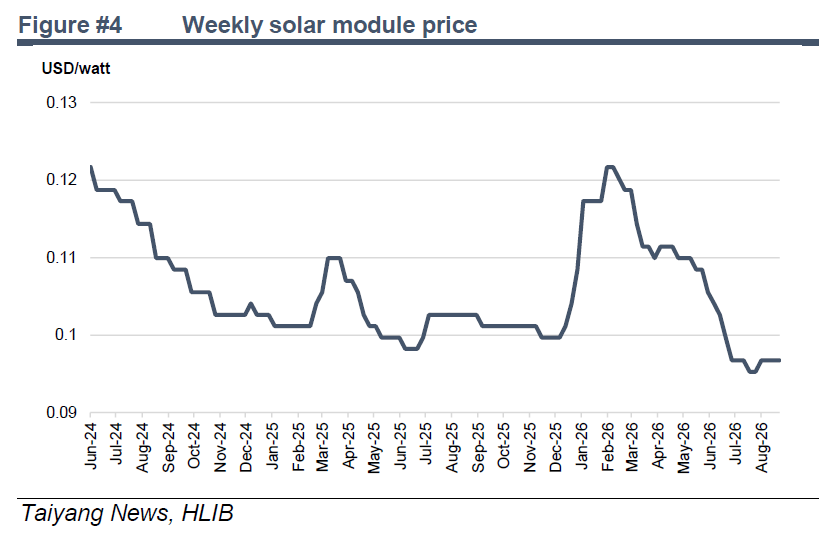
This should improve developers’ project economics and provide a stronger incentive to prioritise CRESS opportunities.
Note that the 30% RE requirement for DCs could be a surprise catalyst. Underpinning the acceleration in CRESS is Malaysia’s rapidly expanding DC sector.
The Data Centre Task Force has recently approved an additional 5GW of capacity, equivalent to 60% of the existing 8.3GW pipeline as at June, further reinforcing the scale of potential electricity demand.
“Crucially, our industry channel checks suggest that newly approved DC projects could be subject to a minimum 30% RE requirement,” said HLIB.
This could turn the additional 5GW pipeline into a sizeable total addressable market (TAM) for RE and provide a meaningful structural catalyst for CRESS adoption.
“While we understand that legacy projects with signed electricity supply agreements (ESAs) may be grandfathered from the requirement, global DC operators’ continued commitment to ESG and RE targets should support sustained demand for green power,” said HLIB.
Based on their scenario analysis of DC capacity and power consumption, HLIB estimated that the resulting incremental energy demand could be substantial and potentially create a multi-year growth opportunity for the RE sector.—Sept 21, 2026
Main image: sustainabilityonline.net