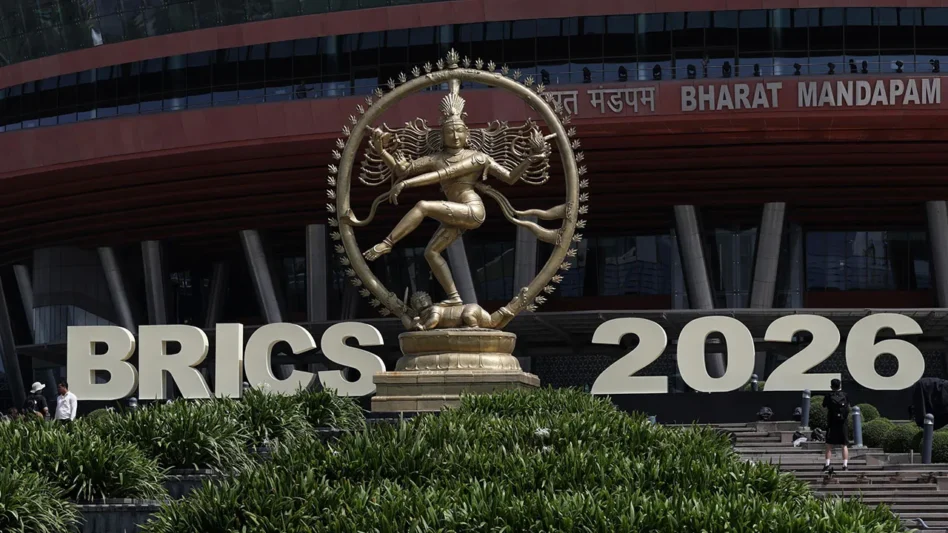
BY the time Prime Minister Datuk Seri Anwar Ibrahim left New Delhi, much of the public conversation had gravitated towards his impromptu rendition of a Kishore Kumar classic at the piano, a moment of soft diplomacy that captured attention far beyond the summit hall.
Yet amid the lighter moments, one important point from the 18th BRICS Leaders’ Summit received far less attention.
In his intervention, Anwar identified Islamic capital markets as one of the areas Malaysia should pursue through its BRICS partnership, alongside trade diversification, semiconductors and artificial intelligence.
Since then, however, the discussion has largely followed a familiar pattern: what Malaysia can offer BRICS.
Islamic finance is often presented as a mature Malaysian export waiting to be shared with less-developed markets. Far less attention has been paid to whether the relationship could run both ways.
The more useful question is not what Malaysia can teach BRICS about Islamic finance. It is where Malaysia and its BRICS partners each hold a missing half of the same problem, and whether Malaysia is prepared to convene that exchange rather than simply showcase its own expertise.
Nowhere is this clearer than in financing halal small and medium enterprises (SMEs), a challenge facing every BRICS economy with a meaningful halal sector and one that no country has fully solved.
A structural mismatch, not a values gap
Many halal SMEs, particularly exporters, struggle to access formal credit not because their businesses are weak, but because conventional collateral-based lending often fails to reflect how they operate.
Their value frequently lies in inventory, supplier relationships, export contracts and certification rather than fixed assets such as land or buildings.
A halal exporter may have verified orders, a strong certification record and a healthy business pipeline, yet still fall short of conventional credit assessments built around property-backed security.
This is fundamentally a financing-architecture problem before it is a religious one.
That is where Islamic banking and trade finance offer practical tools rather than symbolic alternatives. Instruments such as commodity murabahah (cost-plus-profit sale), musharakah (joint-venture financing) and supply-chain sukuk provide ways to translate operational strength into bankable risk.
Malaysia has already developed many of these capabilities. SME Bank, now part of the Bank Pembangunan Malaysia group, has experience with Shariah-compliant financing tailored to SMEs.
What remains missing is a shared cross-border framework that allows halal certification and commercial data to become portable, enabling a certification history in one BRICS market to become meaningful to lenders in another.
Without that portability, each country’s halal SME financing effort remains largely a domestic solution.
Where Malaysia is still the student
The opportunity, therefore, is not to export a finished Malaysian model. It is to convene a platform where different BRICS economies can compare, refine and adapt their approaches.
One practical step would be a BRICS Halal SME Finance Working Group tasked with developing shared standards for translating halal certification into underwriting-ready financial information across borders.
It is a less glamorous proposal than launching another sukuk initiative, but it addresses the kind of operational problem that often determines whether SMEs receive financing.
Malaysia’s regulators and Shariah scholars are well placed to chair such an effort, not because Malaysia has all the answers, but because its Islamic finance ecosystem has earned considerable international credibility.
That distinction matters. A convenor creates the space for competing standards to meet. A vendor simply promotes its own model.
Such a group would also have to confront difficult realities. Data privacy rules differ significantly across BRICS jurisdictions, and no regulator can impose its own framework on the rest.
The objective should not be immediate uniformity, but gradual interoperability built through practical collaboration.
A scorecard for convening, not just exporting
Malaysia’s BRICS strategy should ultimately be judged by outcomes that reflect this convening role.
Success should not be measured solely by how much Malaysian expertise is exported. More meaningful indicators would include shared certification-to-financing standards adopted across multiple BRICS markets, SMEs financed under common frameworks, and equally importantly, practices that Malaysia itself adopts from its partners.
Strategic autonomy has value only when it produces capability.
For Islamic finance, that capability will not come from Malaysia performing a familiar solo. It will come from recognising what its BRICS partners are already learning about the same financing challenge and creating a table where those lessons can travel in both directions.
That is how Malaysia moves from being merely a contributor to becoming a convenor. ‒ Sept 23, 2026
The authors are faculty members at the IIUM Institute of Islamic Banking and Finance (IIiBF), International Islamic University Malaysia (IIUM).
The views expressed are solely of the author and do not necessarily reflect those of Focus Malaysia.
Main image: iStock