MALAYSIAN real estate investment trusts (M-REITs) could be entering a more attractive valuation zone despite renewed pressure from rising domestic bond yields.
The yield on Malaysia’s 10-year Government Securities (MGS10) climbed above the 4.0% threshold in early September 2026.
Over the past decade, the MGS10 yield has crossed the 4.0% level on 16 separate occasions.
However, only four of those periods saw yields remain above the threshold for at least one quarter.
The latest increase, in Hong Leong Investment Bank (HLIB)’s view, has been driven by a combination of elevated US Treasury yields and growing expectations of a domestic interest rate hike.
Their economics team anticipates an overnight policy rate hike in the first half of 2027 (1H27).
As REITs are generally viewed as steady divvy yielders, a rise in the domestic risk-free rate makes the latter relatively less attractive, ceteris paribus.
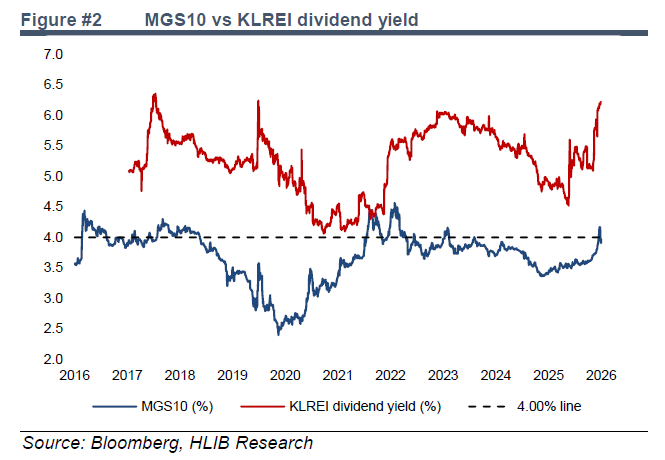
Consequently, the KL REIT (KLREI) index has since fallen 5.6% from its 2H26 high in late Jul-26.
The last episode of sustained elevated MGS10 yields happened from quarter two 2022 (2Q22) to 4Q22, averaging 4.18%.
Over that duration, the KLREI’s dividend yield spread against the MGS10 averaged +77bp.
This was considerably narrower than the current spread of +231bp, suggesting, in HLIB’s, that most of the negatives from a higher domestic risk-free rate environment have been priced in for MREITs.
Given the relatively wider spreads currently witnessed compared to the 2022 period, HLIB sees value emerging amongst M-REITs.
“To reflect the higher domestic risk free rate climate, we raise our MGS10 assumption to 4.0% from 3.7%. Taking a longer term time horizon, we believe that our assumption tilts to the conservative side, as it sits above the 10-year mean of 3.68%,” said HLIB.
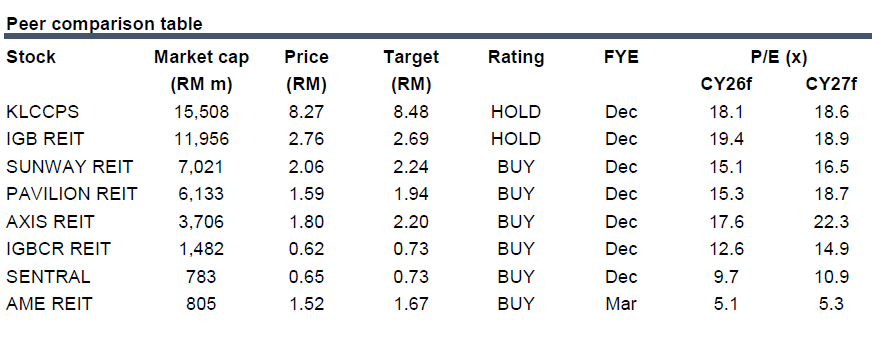
With value emerging, as previously articulated, they upgrade their stance on the sector from Neutral to Overweight.
Operationally, 2Q26 results were broadly intact with five out of seven reviewed REITs meeting or exceeding our expectations and they continue to see sustained earnings delivery in 2H26 across retail, hotel, and industrial subsectors.
“Our top picks are Axis REIT, Pavilion REIT and IGBCR. We also take this opportunity to resume coverage on AMEREIT,” said HLIB.—Sept 23, 2026
Main image: fifthperson.com