TELEKOM Malaysia Bhd (TM) is expected to maintain a positive medium- to long-term outlook, supported by steady performance across its three main business segments –Unifi, TM One and TM Global.
Following a recent meeting with the group’s management, analysts said the growing data centre industry could become an increasingly important growth driver, particularly for TM One and TM Global.
TM is well positioned to benefit from the artificial intelligence (AI) boom through its extensive connectivity infrastructure, which includes the country’s widest fibre network and cross-border connectivity.
This can be complemented by its experience in operating and maintaining data centres, as well as providing enterprise solutions.
The analyst house maintained its “Outperform” call on TM with an unchanged target price of RM9.12, citing stronger demand for connectivity and AI-related infrastructure.
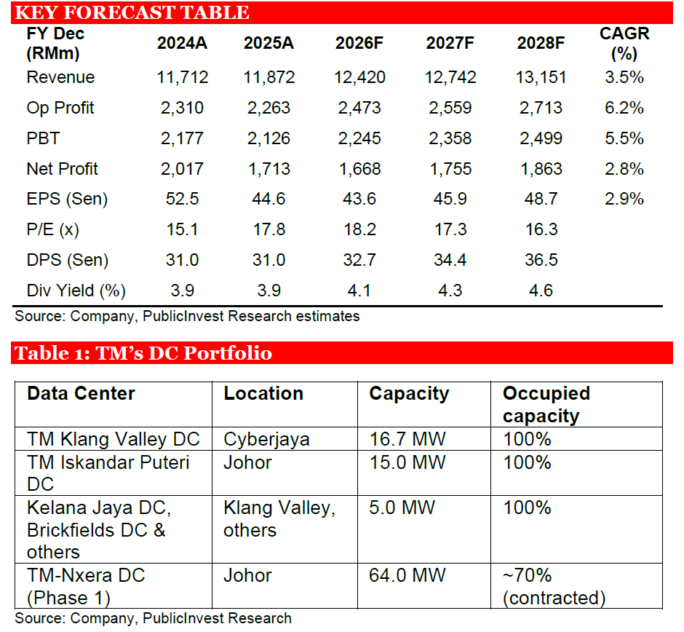
TM’s existing data centre portfolio, with a combined capacity of around 36.7MW, is already fully occupied.
Meanwhile, 16MW out of the 64MW capacity in the first phase of the TM Nxera data centre is expected to become operational this month.
The strong demand could also accelerate the completion of the full TM Nxera facility.
Its eventual capacity of 200MW could be fully delivered by 2029, earlier than the previous target of 2032.
Demand is coming from various sources, including government agencies placing greater emphasis on sovereign data centres, as well as TM’s enterprise customers.
Data centre rates per MW have also increased, with prices rising by double-digit percentages compared with previous levels.
Given the favourable market conditions, TM could explore developing additional data centres to meet growing customer demand.
The group may also consider acquiring existing facilities, forming strategic partnerships or pursuing mergers and acquisitions as alternative ways to expand its data centre capacity more quickly.
Beyond connectivity, TM is also seeking to move further up the value chain by expanding its range of value-added services, including cybersecurity, AI and cloud solutions, for enterprise customers.
A broader portfolio of services could allow TM to provide customers with a more integrated technology ecosystem while increasing their reliance on its platforms and solutions.
For Unifi, the subscriber base is expected to remain broadly stable despite some churn as customers move to competing fixed broadband packages.
However, average revenue per user could receive a boost from stronger demand for bundled offerings, particularly packages that include home security cameras.
TM also hopes to retain customers acquired through its FIFA World Cup campaign by encouraging them to continue subscribing to Unifi TV.
The new customer base could provide opportunities for further cross-selling.
On costs, TM does not expect spending related to the FIFA World Cup campaign to have a material impact on its third-quarter financial performance for 2026.
Meanwhile, management does not anticipate additional expenses from the termination of its 5G access agreement with Digital Nasional Bhd (DNB), following the RM127 mil write-down recognised in the first quarter of 2026.
Costs associated with the group’s voluntary separation programme, known as “Prihatin”, are also expected to have peaked in 2025.
With those expenses expected to ease, manpower costs are projected to come down as TM enters 2027. —Sept 28, 2026
Main image: intraday.my