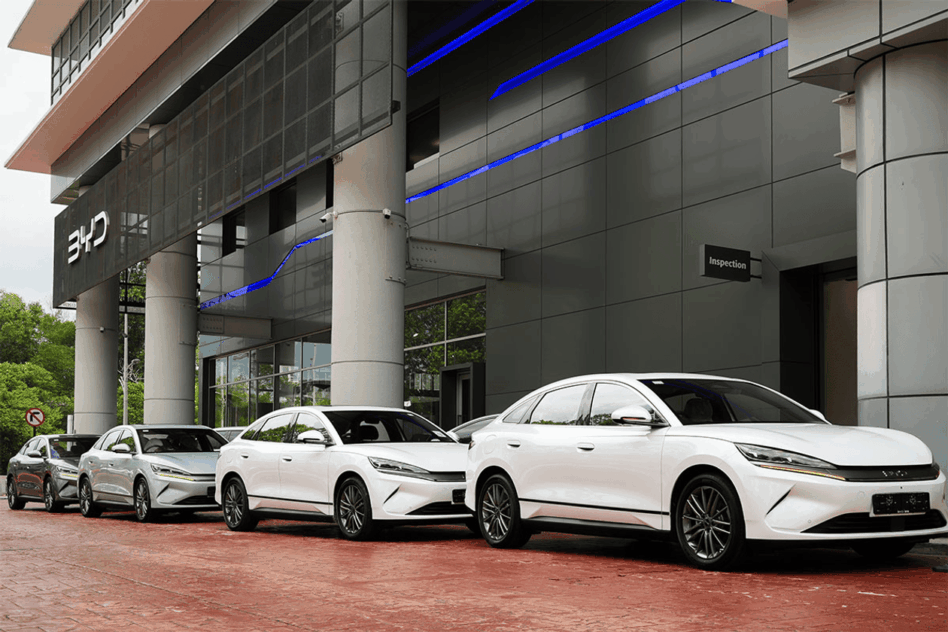
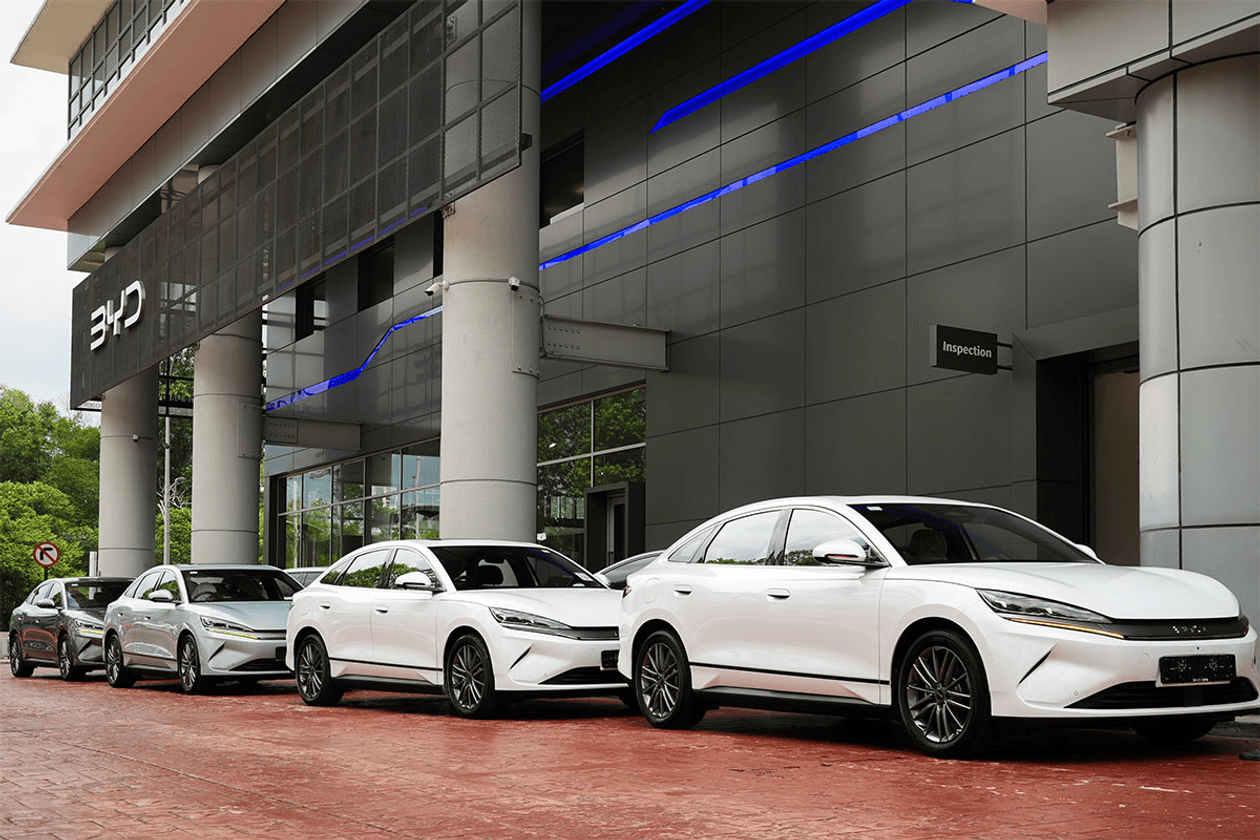
TA Research maintains its Neutral outlook on the local automotive sector following BYD Malaysia’s appointment of Inokom Corporation as its local completely knocked-down assembly partner.
The agreement, formalised through a memorandum of understanding signed in Shenzhen on 15 October 2026, replaces BYD’s earlier plan to establish its own manufacturing plant in Tanjong Malim, Perak.
The partnership allows BYD to leverage Inokom’s existing facilities, workforce and supply chain, potentially accelerating local production while reducing upfront investment.
It may also offer greater flexibility regarding domestic sales restrictions imposed on new manufacturing projects, although the final approval terms remain unconfirmed.
The development could encourage other foreign automakers to pursue local assembly partnerships rather than build new factories.
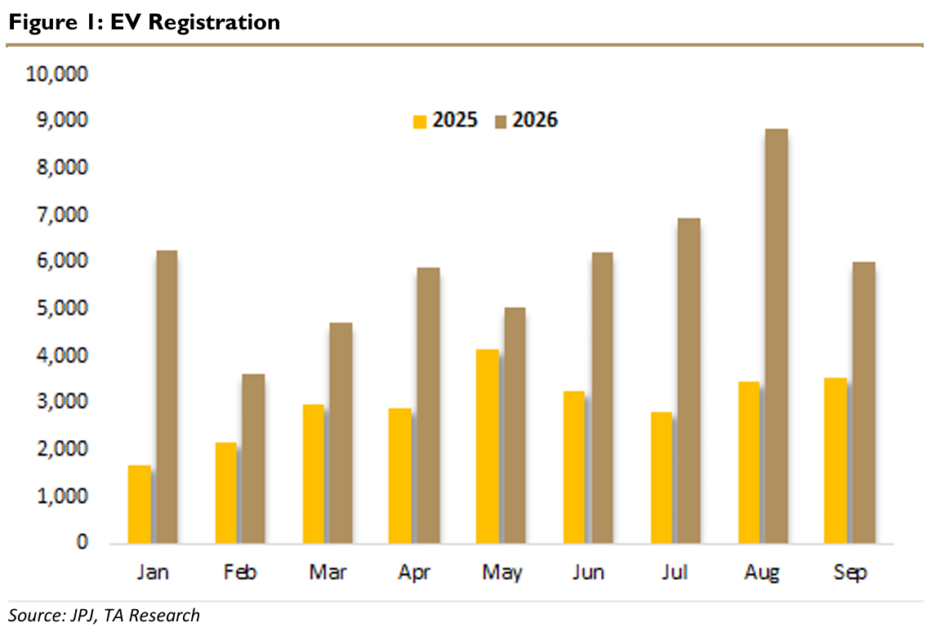
Malaysia’s electric vehicle (EV) market continues to expand rapidly, with registrations nearly doubling by 98.8% year-on-year to 53,500 units in the first nine months of 2026.
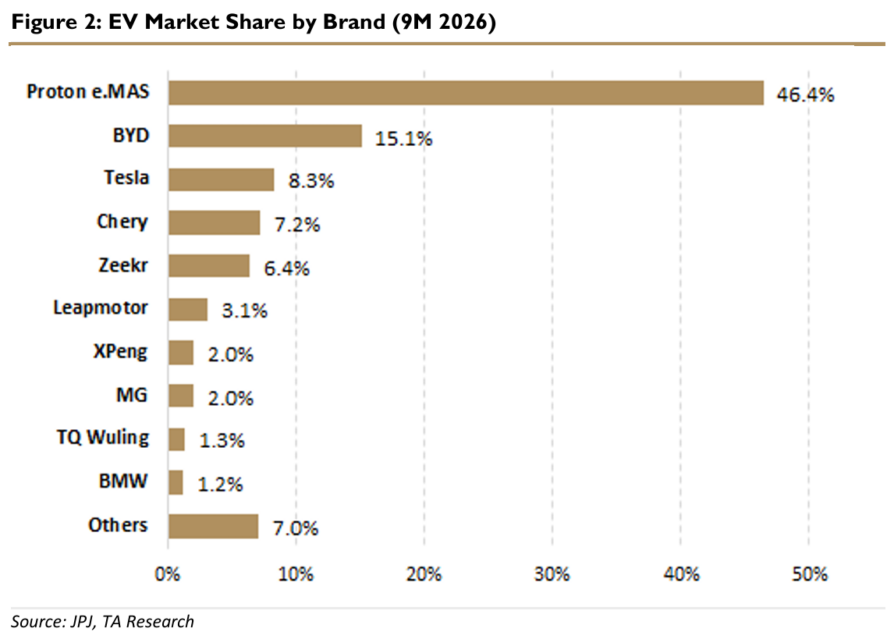
EV penetration rose to 8.4% of new vehicle registrations from 4.4% a year earlier.
Proton e.MAS led the market with 24,900 registrations, followed by BYD with 8,100 units.
Local assembly could improve BYD’s pricing competitiveness and vehicle availability, supporting sales growth.
However, intensifying competition, particularly among Chinese brands, could pressure industry margins if cost savings are passed on to consumers.
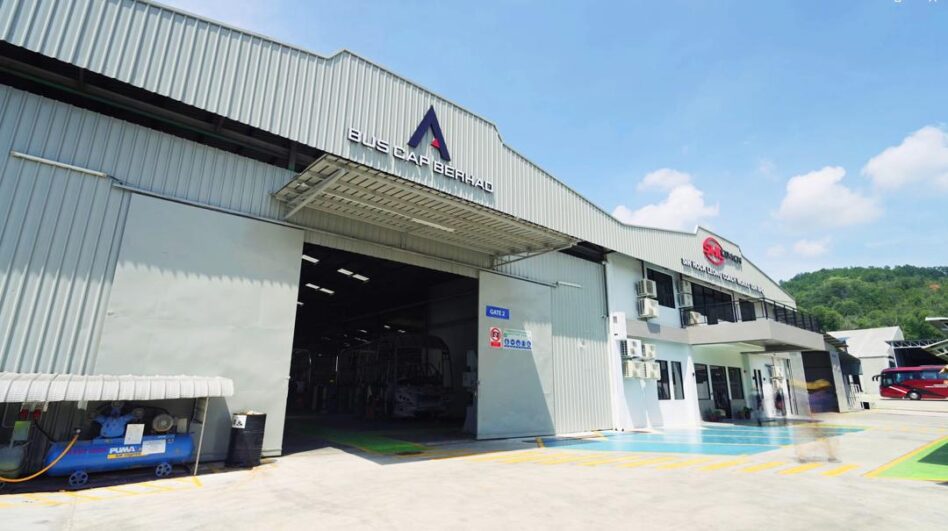
Inokom appears well positioned to accommodate BYD, operating a 200-acre plant in Kulim, Kedah, with more than 2,700 employees and existing assembly operations for six automotive brands.
Production exceeded 31,800 units in 2025, while utilisation currently stands at approximately 80%.
Its new RM300 mil paint shop has doubled annual painting capacity to 100,000 units.
Nevertheless, the impact on capacity and earnings remains uncertain, particularly following Kia’s planned relocation of its assembly operations.
Sime Darby (SIME) could benefit from contract assembly income and vehicle distribution, while Bermaz Auto (BAUTO), which owns a 29% stake in Inokom, may gain from higher associate earnings.
BYD will fund model-specific capital expenditure, limiting additional investment requirements for BAUTO.
TA Research estimates that assembling 10,000 vehicles annually at RM500 incremental net profit per unit could generate RM5 mil in additional net profit for Inokom.
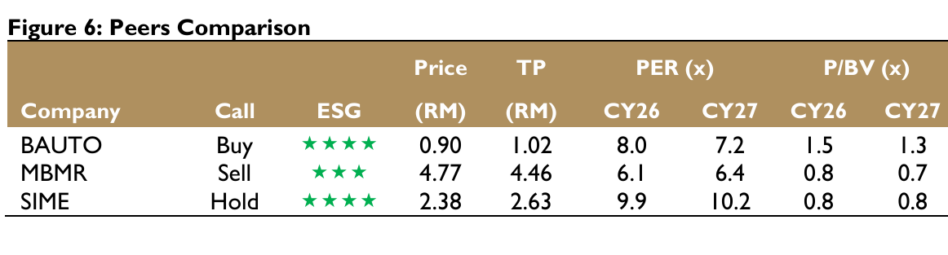
SIME’s attributable contribution would be approximately RM2.7 mil, while BAUTO could recognise RM1.5 mil in associate earnings, representing less than 1% of each company’s forecast FY2027 core earnings.
The research house maintains BUY on BAUTO with a target price of RM1.02 and HOLD on SIME at RM2.63, noting that the partnership’s earnings contribution is likely to be modest.
Mazda’s sales and margin recovery remains BAUTO’s key earnings driver.—Oct 19, 2026
Main image: bitauto.my