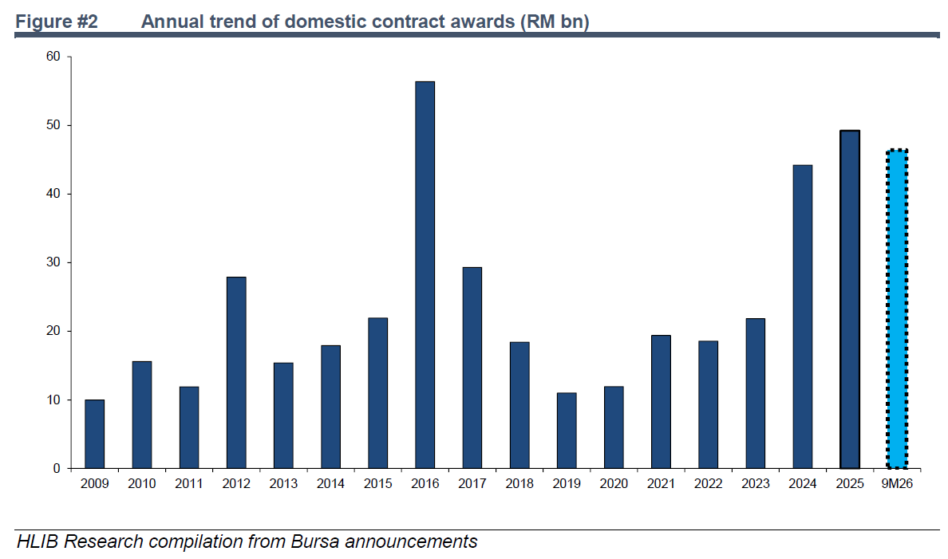
DOMESTIC contract awards for the local construction sector reached RM18.7 bil in the third quarter of 2026, rising 10% quarter-on-quarter and 75% year-on-year.
This brought the nine-month total to RM46.4 bil, up 17% from a year earlier.
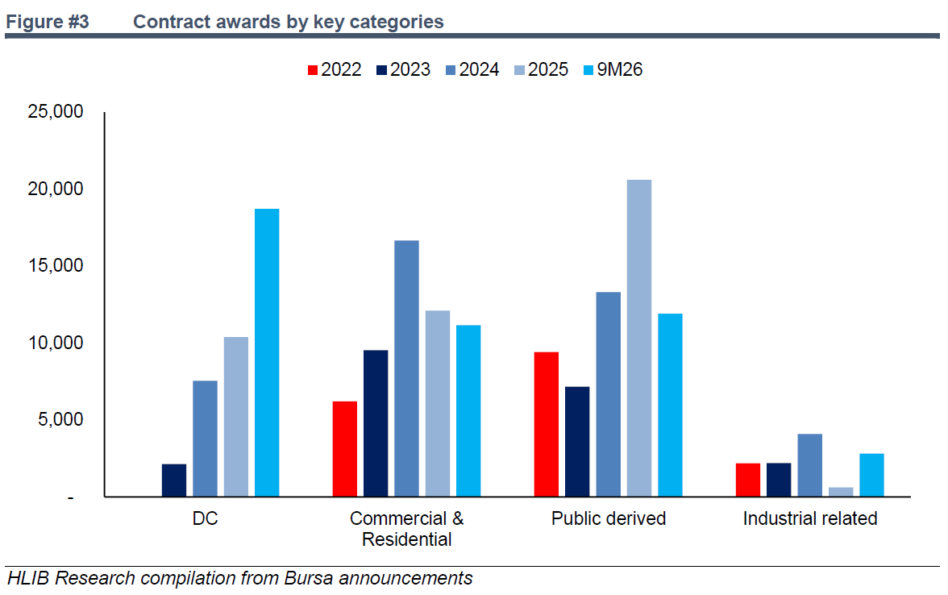
The growth was largely driven by data centres, which accounted for RM10 bil in awards during the quarter, alongside improving commercial and residential project conversions.
Infrastructure activity also remained resilient following the finalisation of the RM3 bil Penang Mutiara Line light rail transit systems package.
Notable wins included Gamuda’s three hyperscale data centre packages in Port Dickson worth a combined RM5.3 bil, the Penang LRT systems contract secured by the MRCB-Theta Edge joint venture, and Kerjaya Prospek’s maiden data centre contract worth RM858 mil.
On that note, Hong Leong Investment Bank (HLIB) maintained its Overweight recommendation on the construction sector, citing strong data centre contract awards and the expanding pipeline of infrastructure and renewable energy projects.
Overseas projects also contributed to contractors’ order books.
According to HLIB, Kelington Group secured RM1.8 bil in turnkey services for a semiconductor wafer fabrication facility in India, while Gamuda won energy and infrastructure projects in Australia.
HLIB believes the construction sector could record its highest annual domestic contract awards in 2026, surpassing the previous record of RM56 bil achieved in 2016.
A healthy pipeline of data centre projects is expected to support fourth-quarter activity, alongside potential Northern Perak water infrastructure and Penang LRT CMC2 packages.
Looking towards 2027, the rollout of Corporate Renewable Energy Supply Scheme projects could provide another source of contract flows.
The report said the previously reduced system access charge of 14 sen per kilowatt-hour, together with an end-2028 commercial operation deadline, could encourage green power demand, particularly as newly approved data centre projects face a 30% renewable energy requirement.
Other potential drivers include the Johor electric autonomous rapid transit project, although the timing of MRT3 remains uncertain.
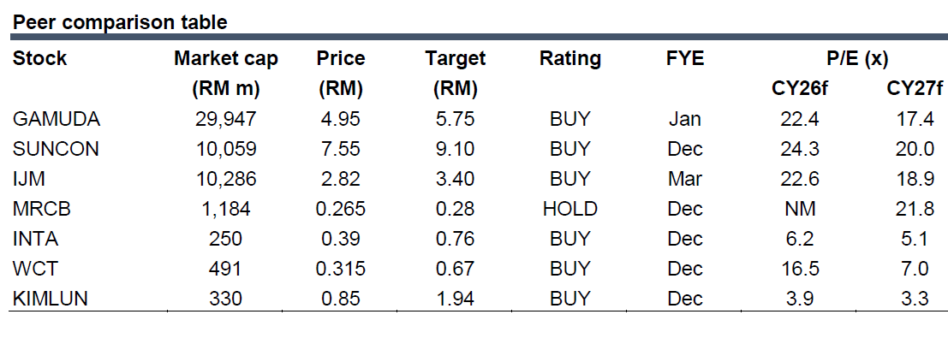
HLIB favours Gamuda as its preferred large-cap pick, with a target price of RM5.75, and Inta Bina as its preferred small-cap choice, with a target price of 76 sen.
It expects sustained data centre construction, semiconductor facilities and renewable energy developments to support contractors and mechanical and electrical engineering players.—Oct 14, 2026
Main image: Unsplash