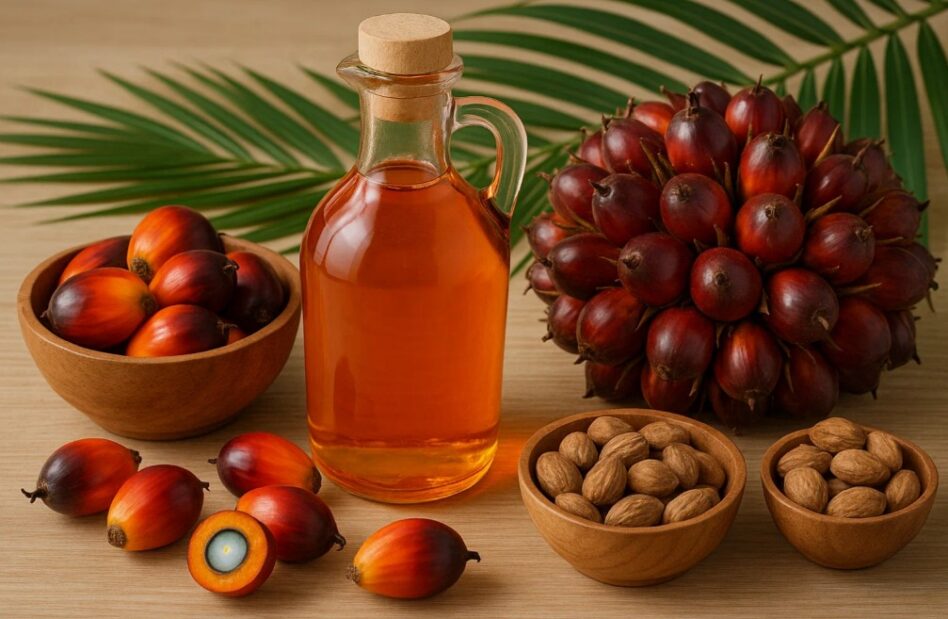
THE plantation sector could receive a boost from a proposed crude palm oil (CPO) export tax waiver, which Public Investment Bank (PIB) believes would help local exporters regain market share from Indonesia.
In its Oct 20 sector update, the research house maintained its “Overweight” rating on plantations, naming Sarawak Plantation Bhd and Ta Ann Holdings Bhd as its top picks due to their attractive dividend yields of 7% to 9% and above-industry-average fresh fruit bunch (FFB) production growth.
Malaysia’s CPO exporters face mounting inventory pressure as the country’s 10% export tax puts them at a disadvantage against Indonesia, where combined export taxes and levies amount to US$273 per tonne, or RM1,113.
This has contributed to a RM700 to RM900 per tonne price discount for Indonesian palm oil compared with Malaysian CPO.
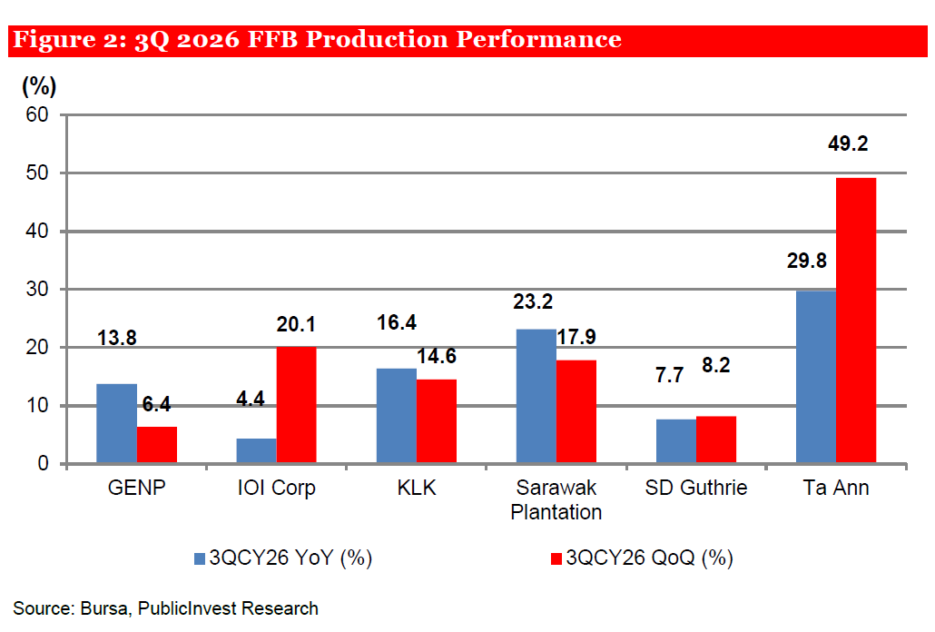
Malaysia’s palm oil inventories reached a record 3.5 mil tonnes last month, while Indonesian exports continued to grow.
PIB believes waiving the export tax, set at 10% for November, would be a timely measure following India’s reduction of its CPO import tax to 5% from 10%.
It recommends maintaining the waiver until Malaysian inventories fall below two mil tonnes.
The proposed measure would benefit upstream plantation companies, although downstream players could face margin pressure from higher raw material costs.
PIB also expects strong third-quarter 2026 earnings from most plantation companies, supported by higher production, lower costs and firmer CPO selling prices.
Average CPO prices rose to RM4,552 per tonne in the quarter, compared with RM4,275 a year earlier.
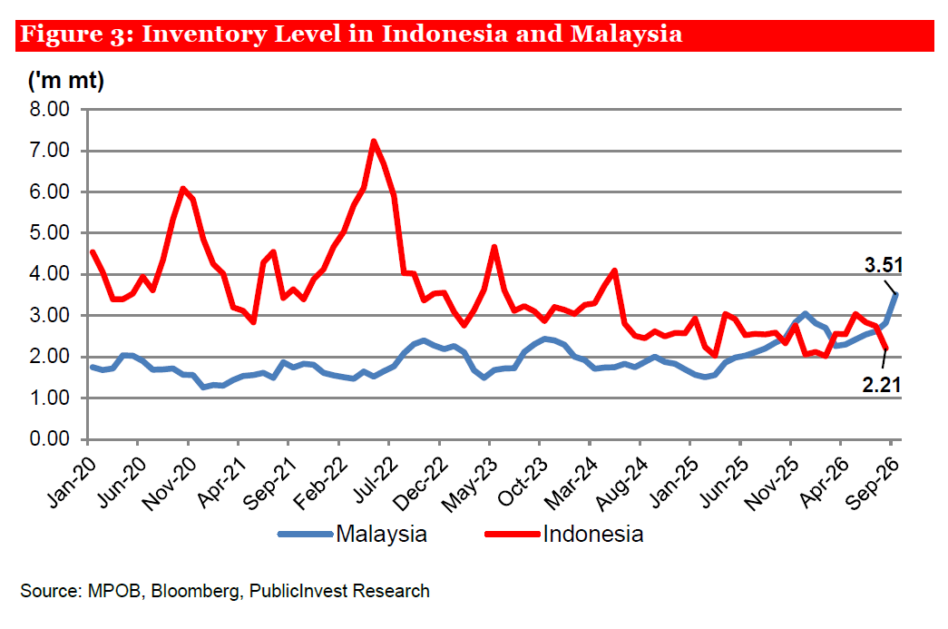
Ta Ann recorded the strongest year-on-year FFB production growth at 30%, followed by Sarawak Plantation at 23.2% and Kuala Lumpur Kepong Bhd at 16.4%.
Favourable weather and improving tree age profiles supported the increases.
The research house expects earnings to strengthen in the second half of 2026, with significant margin expansion.—Oct 20, 2026
Main image: Palm Oil Wiki