THE plantation sector is expected to deliver stronger earnings in the third quarter of 2026, supported by seasonal improvements in fresh fruit bunch (FFB) production and broadly higher palm product prices.
Hong Leong Investment Bank (HLIB) expects results from plantation companies under its coverage to be broadly in line with forecasts, maintaining its “Overweight” rating on the sector.
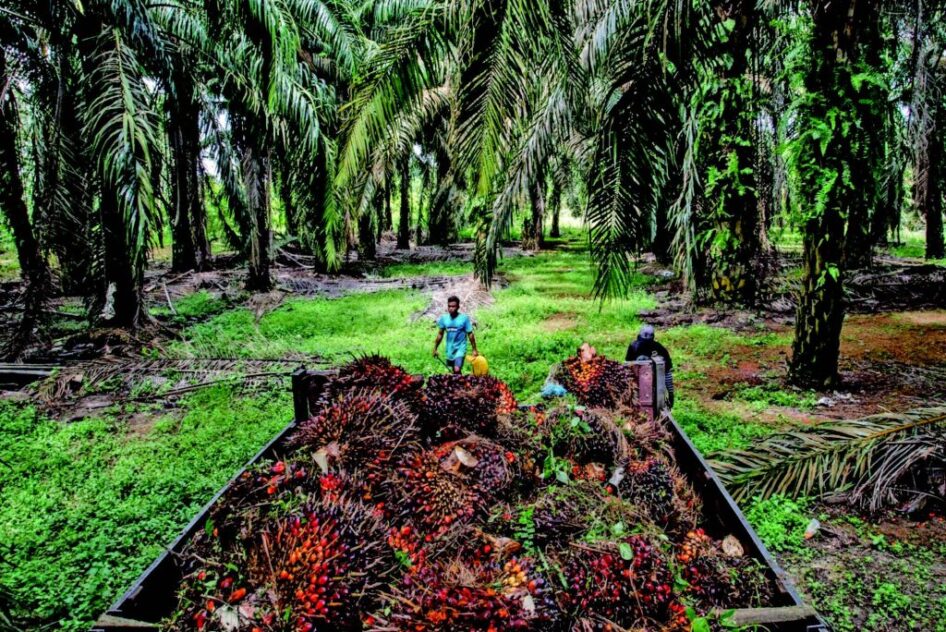
FFB production among covered companies rose between 6% and 35.6% quarter-on-quarter (QoQ) in 3Q26, benefiting from the seasonal cropping upcycle.
Malaysia-focused planters, including Hap Seng Plantations (HSP), Johor Plantations Group (JPG) and IOI Corporation, recorded stronger sequential volume growth than their Indonesian peers.
Upstream earnings are expected to improve QoQ, supported by higher output and broadly stable palm product prices.
However, higher fertiliser costs could partly offset the gains. JPG is an exception, with its output affected by accelerated replanting and prolonged moisture stress that reduced yields.
Downstream profitability is expected to receive near-term support from a narrower crude palm oil (CPO) export tax differential compared with the previous quarter, stable palm kernel prices and proactive restocking amid geopolitical uncertainties and the impending implementation of the European Union Deforestation Regulation (EUDR).
However, refining margins remain under pressure year-on-year due to a wider CPO export tax differential and persistent industry overcapacity.
Active restocking in the oleochemical segment could partly mitigate the pressure.
HLIB maintains its average CPO price assumptions at RM4,450 per tonne for 2026 and RM4,500 per tonne for 2027, supported by an anticipated tightening in supply and demand.
Higher Indonesian biodiesel demand and potential El Niño-related production losses are expected to constrain supply, while demand remains resilient.
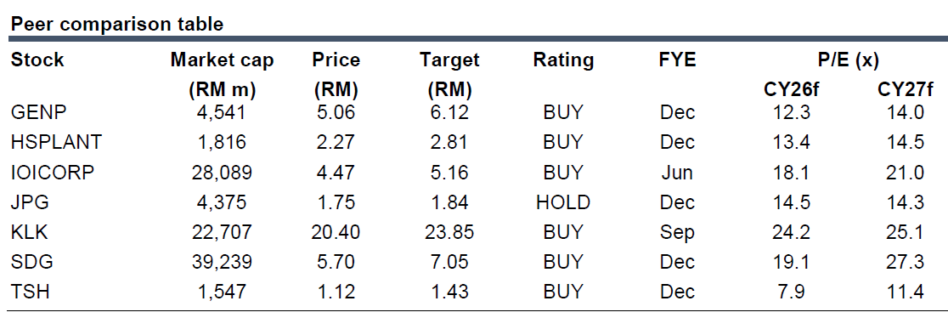
The research house continues to favour plantation companies with greater exposure to Malaysia, naming HSP and IOI Corporation as its top picks.
Overall, HLIB expects elevated CPO prices to remain supportive of plantation earnings into 2027, underpinning its positive sector outlook.—Oct 27, 2026
Main image: Asia School Of Business