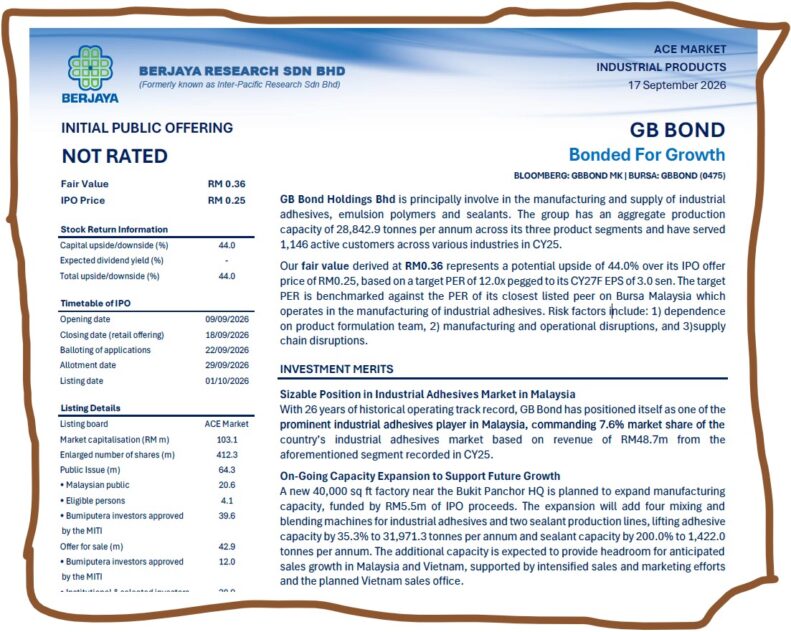
BERJAYA Research has ascribed a fair value of 36 sen/share or 44% potential upside over the 25 sen initial public offering (IPO) price of ACE Market-bound GB Bond Holdings Bhd, a prominent industrial adhesive player.
IPO application for the Penang-based manufacturer and supplier of water-based industrial adhesives, emulsion polymers and sealants closes today (Sept 18) with listing slated for Oct 1.
The valuation is based on a 12.0x target PER (price-to-earnings ratio) pegged to the group’s CY2027F earnings per share (EPS) of 3.0 sen.
“The target PER is benchmarked against the PER of its closest listed peer on Bursa Malaysia which operates in the manufacturing of industrial adhesives,” projected the research house in a recent IPO note.
“The group’s risk factors include (i) over-dependence on its product formulation team; (ii) manufacturing and operational disruptions; and (iii) supply chain disruptions.”
Delving further on prospects, Berjaya Research is impressed with the group’s “sizable position in Malaysia’s industrial adhesives market”.
“With 26 years of historical operating track record, GB Bond has positioned itself as one of the prominent industrial adhesives players in Malaysia by commanding 7.6% market share of the country’s industrial adhesives,” observed the research house.
“As of CY2025, the manufacturing and sale of industrial adhesives segment make up to RM47.1 mil or 92.9% of the group’s total revenue followed by the manufacturing and sale of emulsion polymers at RM3.7 mil (7.0% of group’s total revenue) and remainder from manufacturing and sale of sealants at RM54,000 (0.1% of group’s total revenue).”
On the group’s on-going capacity expansion to support future growth, Berjaya Research pointed to a new 40,000 sq ft factory near its Bukit Panchor headquarters – to be funded by RM5.5 mil of IPO proceeds – which has been planned for that purpose.
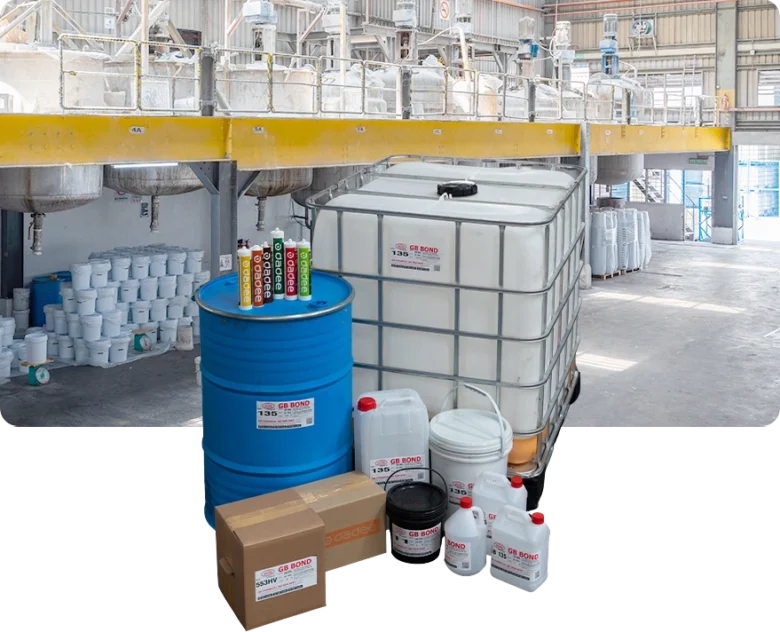
The expansion will add four mixing and blending machines for industrial adhesives and two sealant production lines, lifting adhesive capacity by 35.3% to 31,971 tonnes per annum and sealant capacity by 200.0% to 1,422.0 tonnes per annum.
The additional capacity is expected to provide headroom for anticipated sales growth in Malaysia and Vietnam, supported by intensified sales and marketing efforts and the planned Vietnam sales office.
With regard to earnings growth prospects, Berjaya Research expects GB Bond’s net profit to deliver further improvement, fuelled by strong sales volume across both its industrial adhesives and emulsion polymer segments amid improving demand and deeper penetration into the overseas market – especially Vietnam – while its sealant segment gradually pick-up.
“This follows a two-year CAGR (compound annual growth rate) in core net profit of 26.4% to RM8.1 mil in CY2025,” envisages the research house.
“The rising demand will also be supported by better operational efficiencies and economies of scale from newly installed machineries and favourable product mix.”
The group has an established customer base with 1,146 active customers as of CY2025 spanning both domestic and regional markets with Malaysia serving as its key market alongside overseas markets such as Vietnam, Thailand and Indonesia.
On this note, GB Bond’s revenue for 2Q FY2026 ended June 30, 2026 inched up 13.3% quarter-on-quarter (qoq) to RM15.26 mil, up from RM13.54 mil in the preceding quarter.
The group’s top-line growth translated into a 61.8% qoq rise in pre-tax profit to RM4.18 mil while net profit surged 73.0% qoq to RM3.29 mil (1Q FY2026: RM1.90 mil)
For the cumulative six-month period. the group posted revenue of RM28.80 mil, pre-tax profit of RM6.77 mil and net earnings of RM5.19 mil.
The adhesive segment remained the dominant revenue driver, contributing approximately 94.0% of the group’s total top line during the period. – Sept 18, 2026