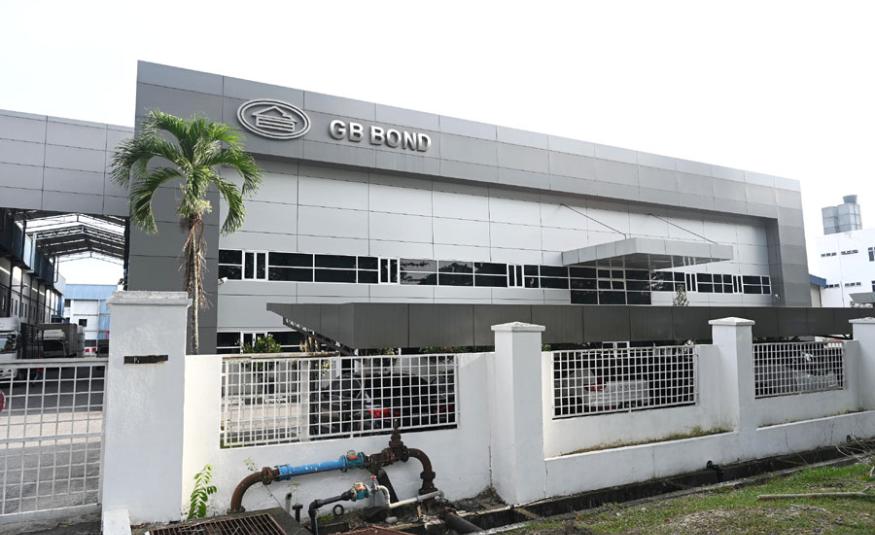
INDUSTRIAL adhesives may not be the first business that catches an investor’s attention.
However, Penang-based GB Bond Holdings Bhd offers a reason to look beyond the product: customised formulations, returning customers and an established manufacturing operation preparing to expand.
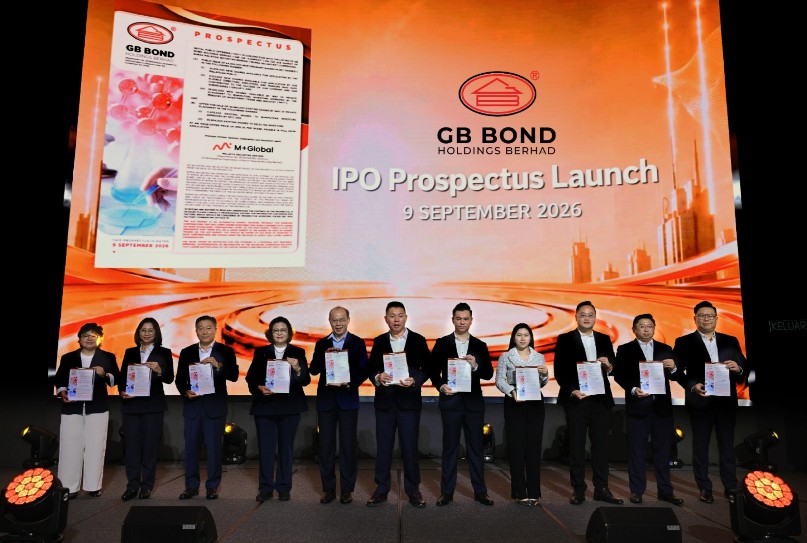
At 25 sen/share, its ACE Market IPO implies a market capitalisation of RM103.08 mil and a historical price-to-earnings multiple of approximately 12.82 times based on FYE2025 adjusted earnings and the enlarged share base.
GB Bond’s IPO applications close on Friday (Sept 18) with listing slated for Oct 1.
During the group’s recent briefing, executive director Gooi Zi Jing explained that GB Bond’s business starts with understanding how customers use its products.
“A packaging manufacturer and a furniture manufacturer may both need adhesives. But their requirements can be very different,” he enthused.
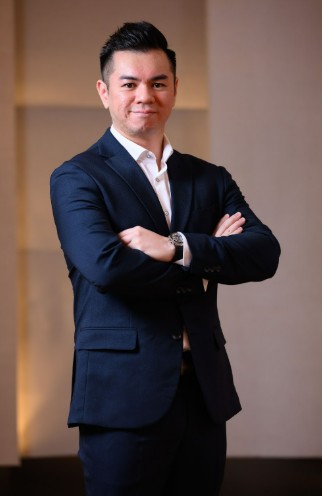
“We work with customers to understand the materials, production process and bonding requirements. Then we develop a suitable formulation.”
More than standard glue
GB Bond sold an average of 409 customised water-based industrial adhesive SKUs (stock-keeping unit) annually between 2021 and 2025.
It also manufactures emulsion polymers in-house, thus giving it greater control over an important input used in its adhesives. These capabilities support product consistency, production turnaround and cost control.
The customer base provides evidence of repeat business. GB Bond served 1,146 customers in FY2025. Approximately 77% had also purchased from the group in one or more of the preceding four financial years.
These are returning customers, not guaranteed contracts. Sales remain purchase-order based. Nevertheless, the pattern of repeat buying is an important part of the investment proposition.

GB Bond recorded revenue of RM52.44 mil and reported net earnings of RM8.20 mil in FY2025. Its gross profit margin improved to 40.23%.
Although its revenue and reported earnings were lower than in FY2024, the group’s adjusted net earnings which excludes disclosed exceptional items including insurance income, declined by a smaller 1.59% to RM8.05 mil.
The latest comparable period in the prospectus showed renewed growth. For the five months ended May 2026, revenue rose to RM24.35 mil. GB Bond’s pre-tax profit firmed 20% to RM6.06 mil while its net profit PAT grew 17.9% to RM4.55 mil. Gross profit margin reached 45.31%.
Lower raw-material costs helped the historical margin improvement. Investors should therefore assess whether those margins can be sustained as input costs and selling prices change.
The balance sheet provides another reference point: RM12.41 mil in cash and bank balances against RM9.18 mil in borrowings as of end-May 2026.
The next catalyst: Capacity and customers
GB Bond’s IPO public issue will raise RM16.08 mil of whuch RM5.50 mil is allocated to new-factory rental and machinery, thus supporting a planned 35.3% increase in annual industrial adhesive capacity to approximately 31,971 tonnes.
Another RM3.50 mil will support the group’s expansion in Vietnam while RM900,000 is earmarked for product-formulation equipment.
“We have been selling to Vietnam since 2009. The next step is to have our own team closer to customers,” envisages Zi Jing who is son of the group’s founder and managing director Datuk Gooi Ching Koay.
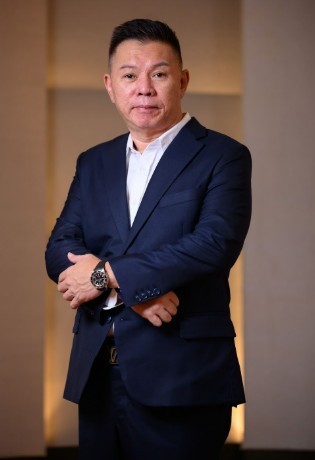
“A local office should help us respond faster, coordinate orders and deliveries and develop new customer relationships.”
The Vietnam plan is for a sales and service operation supported by third-party warehousing, not a manufacturing plant.
The opportunity also comes with a clear execution test. Adhesive utilisation stood at 72.41% in the five months ended May 2026 while the group’s Vietnamese sales during that period were to one customer. More machinery and a new office would translate into additional orders.
All in all, raw-material and currency exposure, rising inventory days and the absence of guaranteed customer volumes also deserve attention.
For investors, GB Bond’s appeal lies in expanding a business that already has customers, technical capabilities and earnings. The catalyst is not simply producing more adhesive. It is winning enough additional business to make that expansion profitable. – Sept 16, 2026