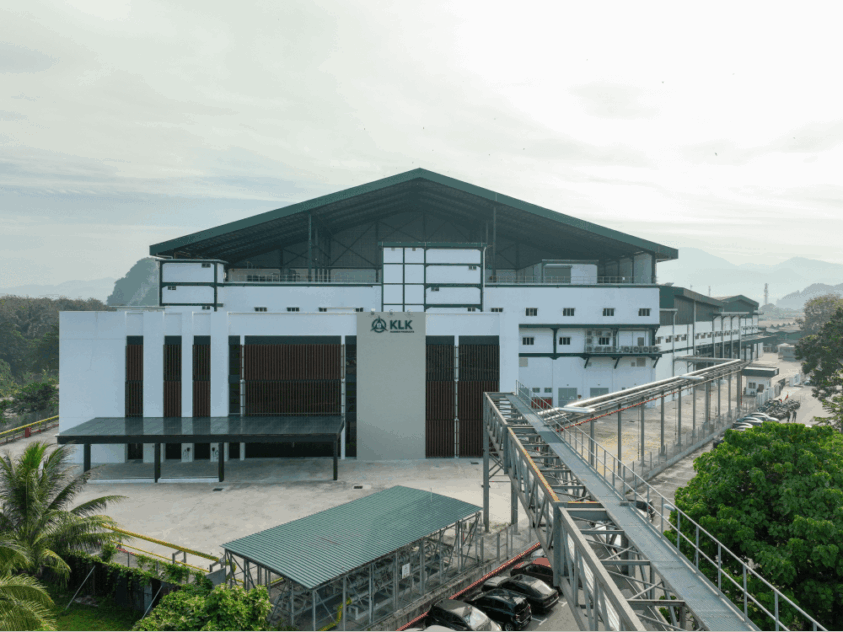
KUALA LUMPUR Kepong (KLK) is expected to deliver a decent performance in the fourth quarter of its financial year ending September 2026 (4QFY26), supported by stronger crude palm oil (CPO) prices and fresh fruit bunch (FFB) production.
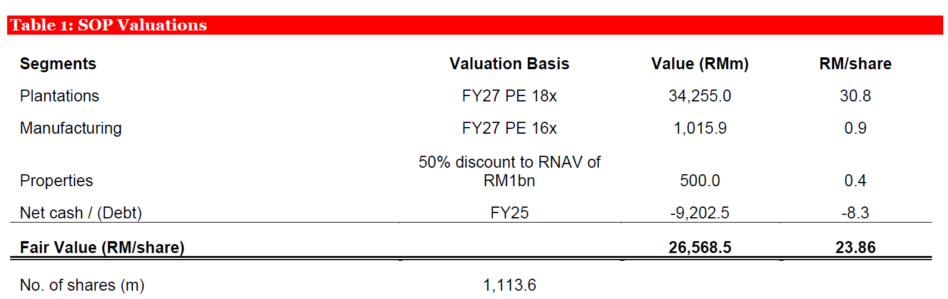
Public Investment Bank (PIB) expects KLK to release its 4QFY26 results on Nov 25, while maintaining its “Neutral” rating and unchanged sum-of-parts-based target price of RM23.86, against a current share price of RM20.54.
Despite positive sales growth, KLK continues to face cost pressures from higher labour and fertiliser expenses.
Malaysia’s minimum wage increase from RM1,700 to RM2,000 monthly is expected to affect approximately 30% of the group’s Malaysian workforce, as the adjustment cascades across employee categories.
Meanwhile, fertiliser procurement costs are forecast to rise 15% to 20% year-on-year.
KLK has secured its fertiliser requirements until February 2027, while PIB expects stronger CPO prices to offset the higher production costs.
KLK’s FFB production reached a record level, surpassing six mil metric tonnes in 2026, representing 7.9% year-on-year growth.
Production in 4QFY26 rose 16.4% to 1.6 mil tonnes. Management indicated that production peaked in October.
Looking ahead, the El Niño phenomenon is expected to adversely affect Indonesian palm oil production next year, although its impact on Malaysian output is likely to be limited.
KLK also plans to accelerate its replanting programme from 2028.
The group expects to replant approximately 7,000 to 8,000 hectares in 2026, with replanting costs averaging RM33,000 per hectare.
The implementation of the European Union Deforestation Regulation (EUDR), scheduled for Dec 30, 2026, could provide another earnings opportunity.
KLK may secure better profit margins for its Roundtable on Sustainable Palm Oil-certified palm oil.
About 100% of its mills and 78% of its estates are currently certified, while the certification premium is estimated at RM100 to RM250 per tonne above standard spot CPO prices.
Beyond plantations, KLK aims to achieve full occupancy at its 2.5-storey Coalfields Retail Park in Sungai Buloh by 1QFY27.
However, the development is expected to take several years to break even.
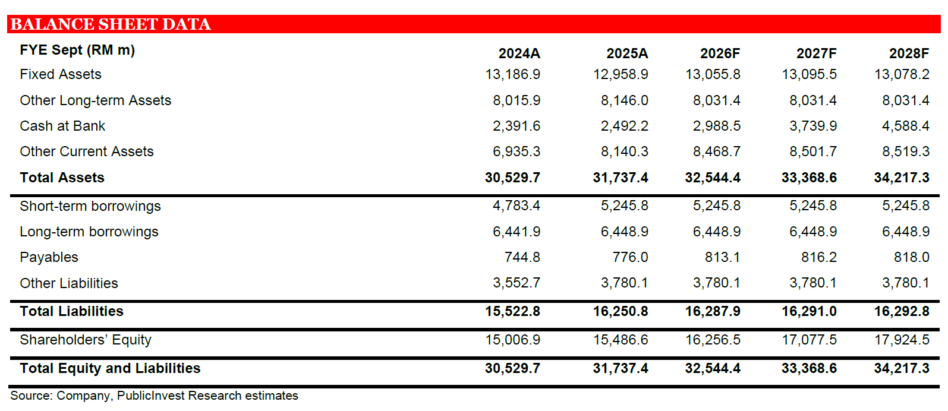
KLK is also exercising caution on capital expenditure, budgeting RM800 mil to RM1 bil for 2026, as it targets reducing gross gearing from 90% to 50% over five years.
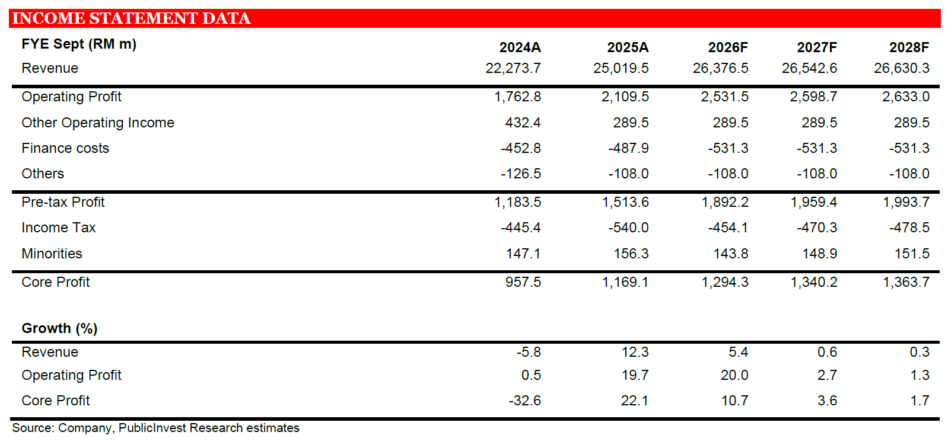
PIB forecasts 2026 core net profit of RM1.29 bil, rising to RM1.34 bil in 2027, as the group balances stronger commodity prices against persistent operating costs.—Oct 28, 2026
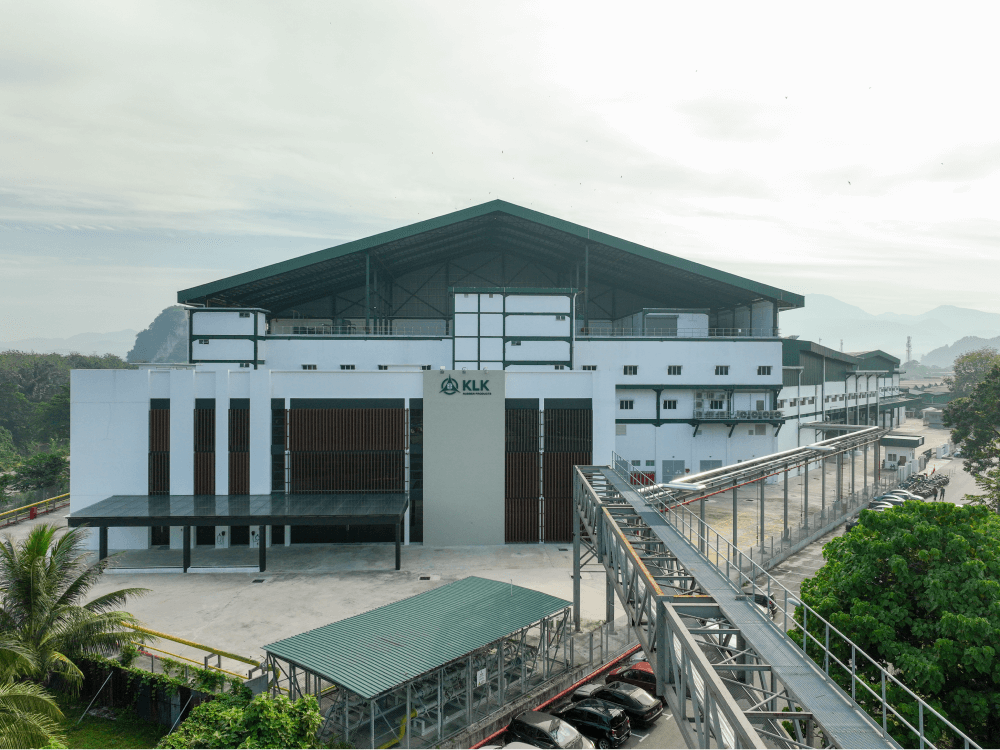
Main image: KLK