THE REIT sector is expected to remain under pressure from higher bond yields, although much of the impact may already be reflected in valuations.
Kenanga Research said the 10-year Malaysian Government Securities (MGS) yield rose from 3.6% in July 2026 to a peak of 4.18%, before easing to about 3.9% in September.
The increase contributed to a 6% decline in the KLREIT Index from its July high.
Meanwhile, the Malaysian REIT Managers Association is engaging the Finance Ministry to seek reinstatement of the withholding tax treatment removed in March 2026.
Although the outcome remains uncertain, Kenanga estimates that reinstatement could trigger a 4% to 5% re-rating in sector valuations.
Separately, IOI Properties Group is preparing to list its proposed IOIPG REIT on Bursa Malaysia, comprising nine assets valued at RM7.7bil, anchored by IOI City Mall Putrajaya.
The listing is targeted for November 2026, subject to regulatory approvals. Kenanga expects the trust to offer an indicative dividend yield of between 6% and 6.8%.
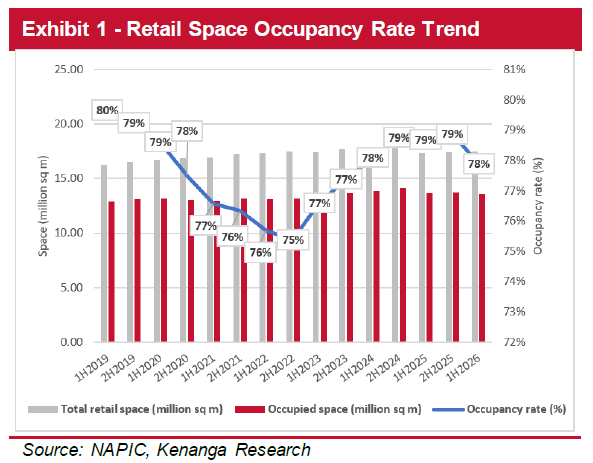
Performance across property segments remains mixed. Retail occupancy eased to 77.9% in the first half of 2026 from 78.9% in the second half of 2025, reflecting cautious consumer sentiment amid Middle East tensions.
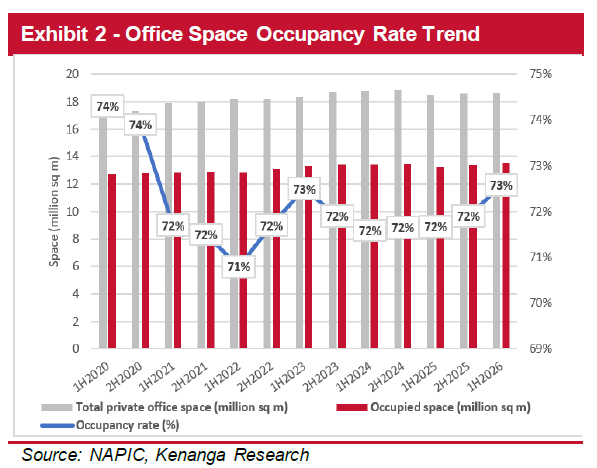
Office occupancy improved to 72.6% from 71.9%, indicating healthier domestic business activity.
Hospitality operators faced a softer first half due to higher airfares and geopolitical uncertainty.
Kenanga expects a gradual recovery if tensions ease, supported by tourism allocations under Budget 2027 and its forecast of 30 mil tourist arrivals in Malaysia in 2026, up 11% from 2025.
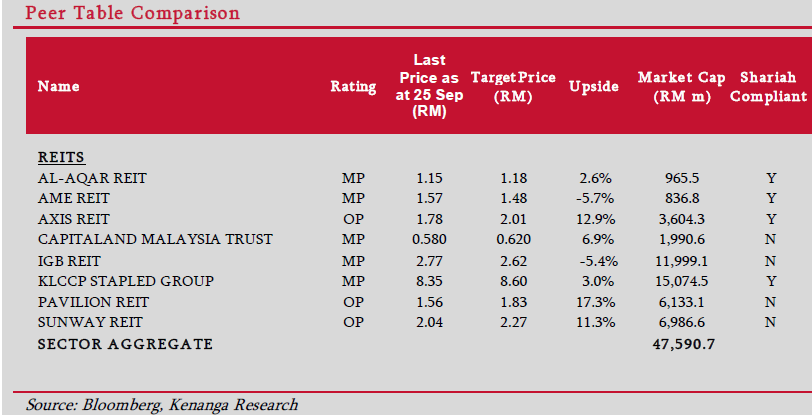
Kenanga retains Pavilion REIT and Sunway REIT as its preferred picks while maintaining “Neutral” on the sector as a whole.
The research house expects limited sector-wide valuation catalysts in the near term amid expectations of a more hawkish US Federal Reserve stance.—Oct 26, 2026
Main image: cmcmarkets.com