NESTLE Bhd’s earnings outlook has strengthened after its nine-month financial year 2026 (9MFY26) results exceeded expectations, driven by lower commodity costs and improved operational efficiency.
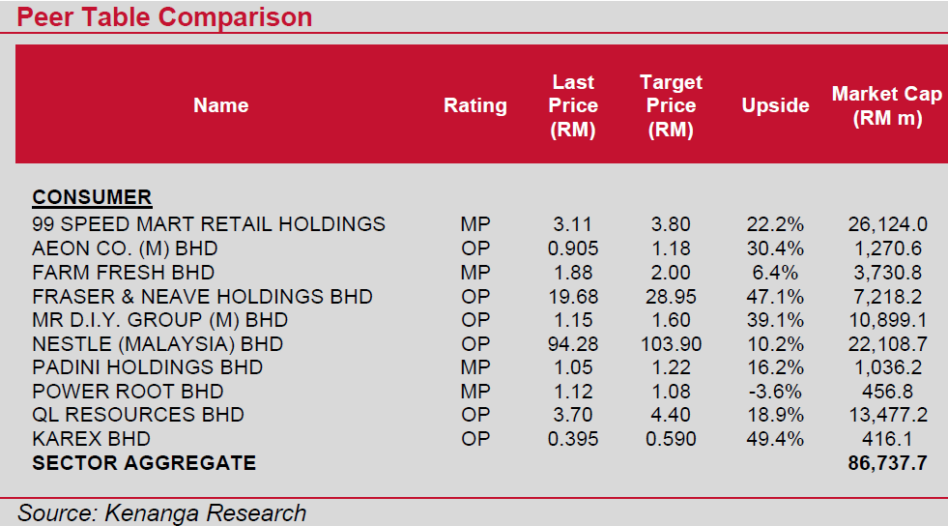
Kenanga Research reiterated its “Outperform” recommendation on the consumer goods group, maintaining its target price of RM103.90.
It also raised its earnings forecasts for FY26 and FY27 by 17% and 9%, respectively, mainly reflecting softer-than-expected raw material costs and continued efficiency gains.
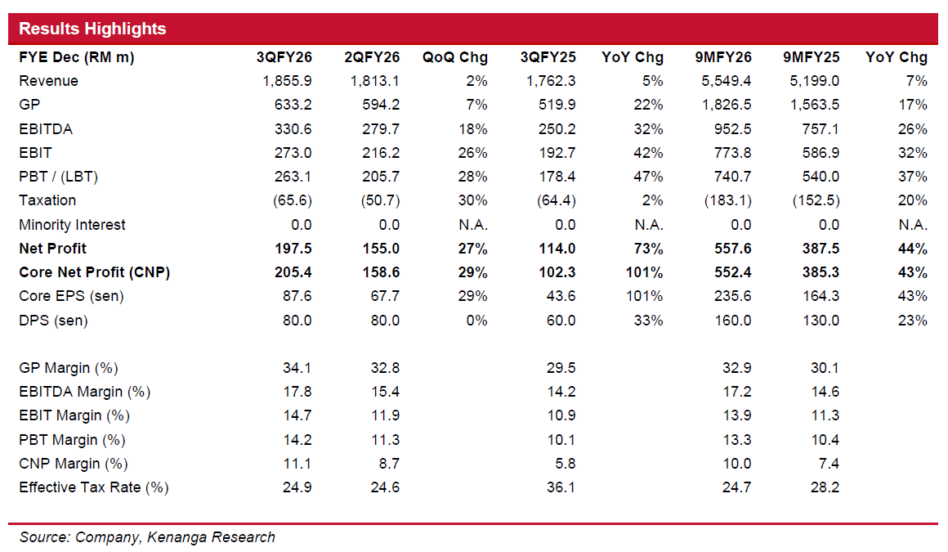
Nestlé’s 9MFY26 core net profit rose 43% year-on-year (YoY) to RM552.4 mil, equivalent to 92% of Kenanga’s full-year forecast.
Revenue increased 7% to RM5.55 bil, supported by stronger domestic sales, which grew 8%, and a 4% increase in exports.
Gross profit climbed 17% to RM1.83 bil, lifting profit margin by 2.8 percentage points to 32.9%.
Lower cocoa and coffee bean costs, favourable foreign exchange movements, reduced finance costs and a lower effective tax rate contributed to the stronger earnings performance.
For the third quarter of 2026, revenue grew 5% YoY to RM1.86 bil, while core net profit more than doubled to RM205.4 mil.
The group declared a dividend of 80 sen per share for the quarter, compared with 60 sen a year earlier.
Kenanga expects potential commodity cost pressures to emerge in 2027 as cocoa and coffee bean prices recover.
However, the research house believes a repeat of the sharp commodity price shock experienced in 2023 and 2024 is unlikely, given healthier supply conditions and a stronger ringgit.
A potential El Niño event remains a risk to global food supplies.
Revenue growth may moderate in the fourth quarter due to a higher base and lower export selling prices.
Nevertheless, domestic demand remains resilient, supported by favourable market share trends and household penetration.
Kenanga also expects Budget 2027 assistance, including expanded SARA cash aid, to support consumer spending.
The upcoming minimum wage increase to RM2,000 in June 2027 is expected to have limited impact, as most employees already earn above the revised threshold.
Despite a roughly 17% share price decline year-to-date, Kenanga sees an attractive accumulation opportunity, citing Nestlé’s established brands, resilient demand and improving margins.
Key risks identified by the research house include rising commodity prices, ringgit weakness and consumers switching to cheaper alternatives.—Oct 28, 2026
Main image: stock.adobe.com