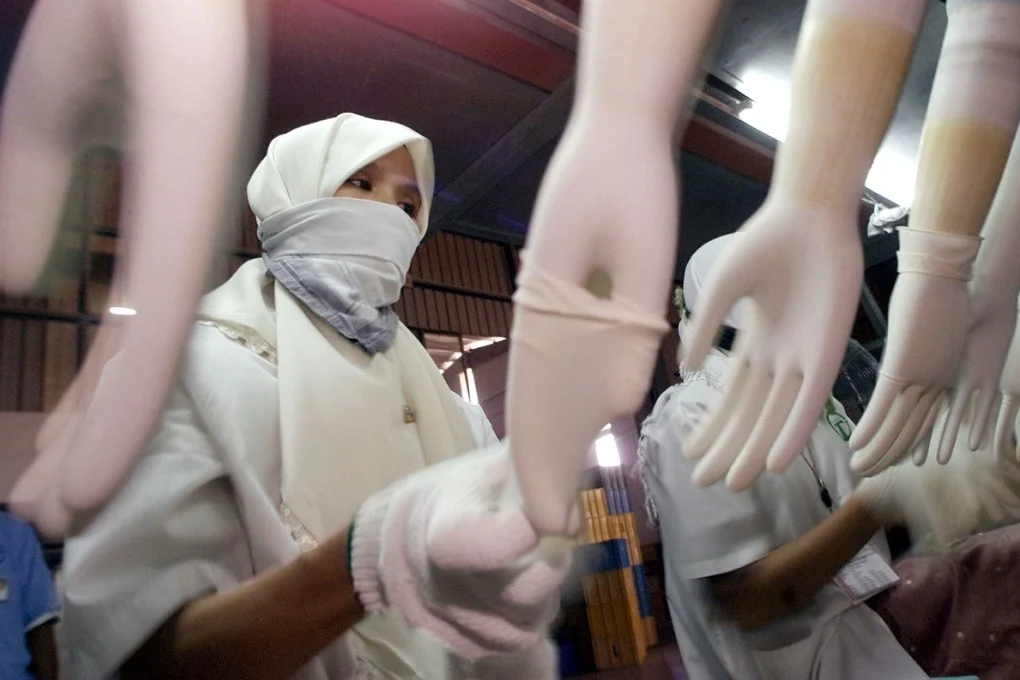
NATURAL gas costs are set to become a bigger concern for glove makers as the sharp rise in crude oil prices threatens to squeeze margins and push selling prices higher.
“We estimate the 45% increase in Brent crude prices in quarter two 2026 (2Q26) could translate into a 37-52% rise in natural gas prices in 4Q26,” said CGS International (CGS).
In response, Chinese glove producers raised average selling prices (ASP) by US$2-3 per 1,000 pcs in early-Sep 2026, with our channel checks suggesting this was a pre-emptive move ahead of potentially similar ASP increases by Malaysian producers.
CGS believes the recent ASP increases are primarily a response to higher natural gas expenses, although rising costs for raw materials and labour could have also played a part.
An assessment of glove manufacturers’ ESG disclosures shows that companies heavily dependent on a single energy source may be more vulnerable to cost pressures, particularly when fluctuations in Brent crude prices eventually affect natural gas costs.
Having a more diversified energy mix and adopting more energy-efficient production methods could help cushion manufacturers from such cost increases.
Among Malaysian glove makers, Top Glove appears to have an advantage, with renewable energy accounting for 22% of its total energy consumption.
Its machinery is also estimated to be 7-13% more energy-efficient than those used by its peers.
“We reiterate our Neutral call on the Malaysian glove sector as valuations now appear to be fairly priced in the earnings recovery,” said CGS.
However, profitability remains subdued and still well below the pre-pandemic range of 18-24%. Kossan is CGS’s sector top pick.
Its increased focus on the higher-margin cleanroom segment could drive an earnings re-rating.
Sector upside risks identified by CGS are public health, geopolitical, or supply chain shocks driving restocking or glove consumption.
Further note the accelerated retirement of legacy capacity; and higher tariff barriers that shift demand away from non-Malaysian producers.
On the other hand, sector downside risks are the further ringgit strength against the US dollar and ongoing capacity additions that extend the oversupply cycle.—Sept 28, 2026
Main image: South China Morning Post